1. Credit and Debt HS
+ Customize lesson
0
0
Sign In
This lesson will teach you the theory required to fully understand the topic and will present both exercises and selftests to gauge your understanding.
Show less Show more expand_more| | 12 Theory slides |
| | 15 Exercises - Grade E - A |
| | Each lesson is meant to take 1-2 classroom sessions |
Long-term decision-making:
Saving vs borrowing:
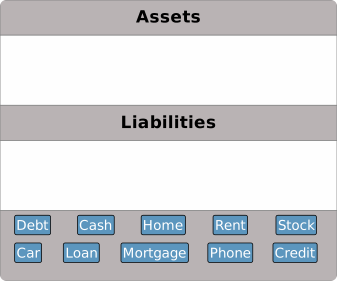
Assets are everything you own that is worth money, like cash, savings, investments, real estate, and valuable items. In other words, an asset is something you own that has value. On the other hand, a liability is something you owe that is a financial obligation.

Sort the items into assets and liabilities. Remember, assets are things that you own that have value and liabilities are things you owe!
A loan is money or property that you borrow with a promise to repay the original amount, called the principal, plus extra charges like interest or fees. Loan repayments can be one-time or ongoing.
 What kinds of loans are there? Explore the diagram below to discover some common types of loans.
The interest rate is the percentage of the principal a lender charges for borrowing money. It tells you how much the loan will cost over time. The simplest way interest can be calculated is through simple interest. Simple interest is calculated only on the principal amount. There is a formula for finding simple interest.
I=Prt
The variables used in the formula are defined as:
Compound interest is interest that is calculated not just on the original loan or deposit — the principal — but also on the interest already added. This concept is often referred to as interest on interest.
In contrast, simple interest is calculated only on the principal amount.
 There is a formula for finding how compound interest affects the balance of a savings account or loan.
A = P(1 + r/n)^(nt)
The variables used in the formula are defined as:
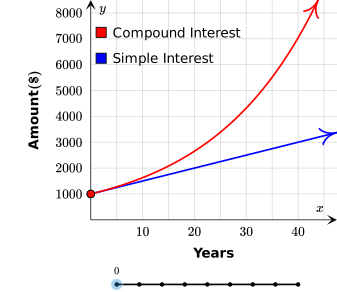
Use the interactive graph to compare simple and compound interest, starting with a $1000 investment and a 5 % annual rate. As you explore, notice how the difference between the two types of interest remains small at first but increases over time, illustrating their distinct effects on your investment.
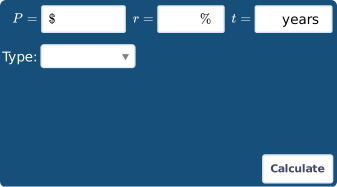
Use this calculator to find simple or compound interest. Enter the required parameters for your specific case and choose the interest type to get the result.
Ethan buys a gaming laptop for $1000 using a credit card with a 20 % annual interest rate, compounded monthly. He was offered a deal where he doesn't have to make any payments for the first year, so he doesn't.

How much will Ethan owe after 1 year? Round to the nearest whole dollar amount.
How much interest did Ethan pay?
What could Ethan have done to avoid paying any compound interest?
Now imagine that Ethan only used the credit card because he wanted to earn points on the card. He pays off his entire balance before the first bill arrives. How much interest does he pay?
Use the compound interest formula.
Subtract the original amount he borrowed from the total he owes after one year.
Think about the fact that the interest compounds each month. What if he pays off the balance in fewer months?
The interest accrues after each month passes. What happens if there is no debt remaining at the end of the first month?
Ethan's initial balance is $1000 and the annual interest rate is 20 %, compounded monthly. We calculate the total amount owed after 1 year, where the interest compounds a total of 12 times, using the compound interest formula.
A = P (1 + rn)^(nt) Remember that, in this formula, P is the principal, r is the annual interest rate written as a decimal, n is the compounding periods per year, and t is the time in years.
Substitute values
Calculate quotient and product
Add terms
Use a calculator
Round to nearest integer
After 1 year, Ethan will owe approximately $1219.
The total interest paid is the difference between the total amount paid and the principal.
$1219 - $1000 = $219 Ethan paid $219 in interest.
Let's consider the given options to determine what Ethan could have done to avoid paying any compound interest.
| Option | Logic | Conclusion |
|---|---|---|
| Pay off the full balance right away. | No balance remains to accrue interest if paid immediately. | No interest will be paid ✓ |
| Buy a cheaper laptop. | A lower purchase amount reduces total interest but doesn’t prevent it from accruing. | Less interest would be paid overall * |
| Pay the balance off in equal payments over the course of the year. | Interest accrues from the first month, but consistent payments reduce the balance faster. | Less interest would be paid overall * |
| Negotiate with the credit card company for better terms and conditions. | A successful negotiation might lower the interest rate but won't guarantee zero interest. | Less interest might be paid * |
If Ethan pays the full balance before the first bill arrives, no interest is charged. Ethan will pay $0 in interest.

When borrowing money, both the interest rate and the annual percentage rate are important to understand.
The annual percentage rate (APR) represents the annual cost of borrowing money, shown as a percentage. It includes the interest rate plus any extra fees or costs associated with the loan.
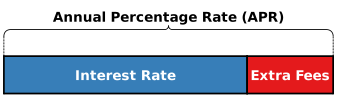
Banks often advertise the interest rate instead of the APR because it's more attractive. This is because the interest rate only shows the cost of borrowing, while the APR includes interest plus fees. APR is usually higher and gives a more complete picture of the total cost of a loan. By highlighting the lower interest rate, banks make their loans appear more appealing.

Layla takes out a $10 000 loan to buy her first car. She is told that the interest rate is 5 %, compounded monthly, and she plans to pay it off in 5 years. She uses this number to build her budget. After reviewing her contract, she learns that there are extra fees included in the loan, which brings the annual percentage rate (APR) to 6 %.

How much did Layla think her total repayment would be (based on 5 % interest)? Round to the nearest whole dollar amount.
What is the actual total cost of the loan (based on 6 % APR compounded monthly)? Round to the nearest whole dollar amount.
What is the difference between what she expected to pay and what she actually has to pay?
Use 5 % as the interest rate in the compound interest formula.
Use 6 % as the interest rate now.
Subtract the expected total from the actual total.
We want to calculate the total repayment Layla expected for her $10 000 loan based on a 5 % interest rate compounded monthly — which means that it happens 12 times every year — for 5 years. Let's recall the formula for compound interest.
A = P (1 + rn)^(nt) In this formula, P is the principal, r is the annual interest rate in decimal form, n is the number of compounding periods per year, and t is the number of years.
Substitute values
Calculate quotient and product
Add terms
Use a calculator
Round to nearest integer
Layla expected to repay $12 834 on her loan.
Now we calculate the actual repayment using the APR of 6 % compounded monthly. Everything about the compound interest formula will remain the same except that r is now 0.06.
Calculate quotient and product
Add terms
Use a calculator
Round to nearest integer
The actual total cost of the loan over 5 years is $13 489.
We subtract the expected repayment from the actual repayment to find the difference.
$13 489 - $12 834 = $655 Layla will have to pay $655 more than she expected.
Loans can help you pay for important things — like a car, college tuition, or even a home — but only if you understand how they really work.

When you borrow money, you're not just paying back the amount you took out — you're actually paying back extra money in the form of interest and possibly fees. That's why it's so important to know:
If you don't read the fine print or don't understand these terms, you could:
Understanding loans now helps you make smarter financial decisions later, so you're in control of your money — instead of your money controlling you.

Match each term with its definition.
Let's match each term with its definition, starting with principal. When you borrow money, you are given a specific amount at the beginning. This initial amount is referred to as the principal.
Principal → The original amount of money borrowed
In addition to returning the borrowed amount, you also have to pay extra for using the money. This extra amount is known as interest.
Interest → The cost of borrowing money
Next, we have APR. This is a yearly rate that shows the total cost of borrowing money, including fees and interest.
APR → Annual cost of a loan including fees
Finally, let's look at asset. An asset is anything you own that has value, such as a house, a car, or savings in the bank.
Asset → Something owned that has monetary value.
Which of the following is the best way to avoid paying interest on a credit card?
Let's go through the options one by one.
| Option | Reasoning |
|---|---|
| A. Only use it for emergencies | This sounds like a good idea, but it does not tell us how to pay back the money we borrow. It is more about when to use the credit card, not how to use it wisely. This is not the best answer. * |
| B. Pay the minimum due each month | This can be a problem because we might end up owing more money in the long run due to interest. Paying only the minimum can take a long time to pay off the debt, and we might end up paying a lot more than we borrowed. That is not a good plan. * |
| C. Pay off the full balance before the due date | This is a great option! If we pay off the full balance, we do not have to pay any extra interest. We can avoid owing more money and pay back what we borrowed quickly. ✓ |
| D. Use all your available credit | This is not a good idea at all! Using all our available credit can lead to owing a lot of money and having trouble paying it back. It is easy to get into debt and struggle to pay it off. * |
The best answer is C.
You are comparing two car loans.
Which loan will likely have the higher APR?
We are comparing two car loans: Loan A and Loan B. Loan A has a 4.5 % interest rate and no fees. Loan B has a 4.4 % interest rate and $400 in yearly fees. We need to figure out which loan will likely have the higher APR, or Annual Percentage Rate.
Let's assume both loans are for $10 000. For Loan A, the interest paid over a year would be 4.5 % of $10 000, which is $450. For Loan B, the interest paid over a year would be 4.4 % of $10 000, which is $440. Interest on$10 000 Loan A:& $450 Loan B:& $440 However, Loan B also has $400 in yearly fees so the total cost for Loan B over a year would be the sum of the interest and the fees. Total cost for$10 000 Loan A:& $450 Loan B:& $440 + $400 = $840
The APR for Loan A is simply the interest rate, which is 4.5 % because there are no fees associated with this loan. Loan A's APR=4.5 % For Loan B, we need to consider both the interest rate and the yearly fees. The effective interest rate is higher than 4.4 % because of the $400 fee. Loan B's APR > 4.4 % Since $400 is a significant fee, it will make Loan B's APR much higher than its 4.4 % interest rate. Therefore, Loan B will likely have the higher APR.
Which of the following will increase the total amount you pay on a loan?
Let's analyze each option one by one.
| Option | Reasoning | Conclusion |
|---|---|---|
| A Lower APR | A lower APR means you are paying less interest on your loan. This will decrease the total amount you pay on a loan. | This option will not increase the total amount. * |
| Making Extra Payments | When you make extra payments, you are paying more than the required amount each month. This will help you pay off the loan faster and reduce the total interest paid. | Making extra payments will decrease the total amount of interest you pay on a loan. * |
| Paying Over a Longer Period of Time | If you take longer to pay off a loan, you will have to make more payments. This means you will pay more interest over time. | The total amount you pay will increase. ✓ |
| Choosing a Shorter Loan Term | Choosing a shorter loan term means you will pay off the loan faster. This typically results in lower total interest paid. | This option will not increase the total amount. * |
The correct option is Paying over a longer period of time
because it is the only one that will increase the total amount you pay on a loan.
What is one key difference between APR and interest rate?
To understand the key difference between the Annual Percentage Rate (APR) and interest rate, let's start by defining each term.
Interest Rate |- The interest rate is the percentage of the principal a lender charges for borrowing money. It tells you how much the loan will cost over time.
In contrast, the APR provides a broader picture of the loan's cost.
Annual Percentage Rate (APR) |- The APR represents the annual cost of borrowing money, shown as a percentage. It includes the interest rate plus any extra fees or costs.
From these definitions, we can spot that a key difference between APR and interest rate is that APR includes both interest and fees, whereas the interest rate only reflects the interest charged on the loan.